Mableton, GA
Trucking Insurance in Mableton With Timelines You Can Plan Around
We place primary auto liability, physical damage, motor truck cargo and bobtail coverage for owner-operators, new-authority carriers and small fleets in Mableton, Smyrna and Austell. You get a straight answer on when each quote and filing should land, and a call from us if an underwriter or a deadline moves.
- Quotes worked by phone
- Realistic filing timelines
- Updates when plans change
- Office, phone or video
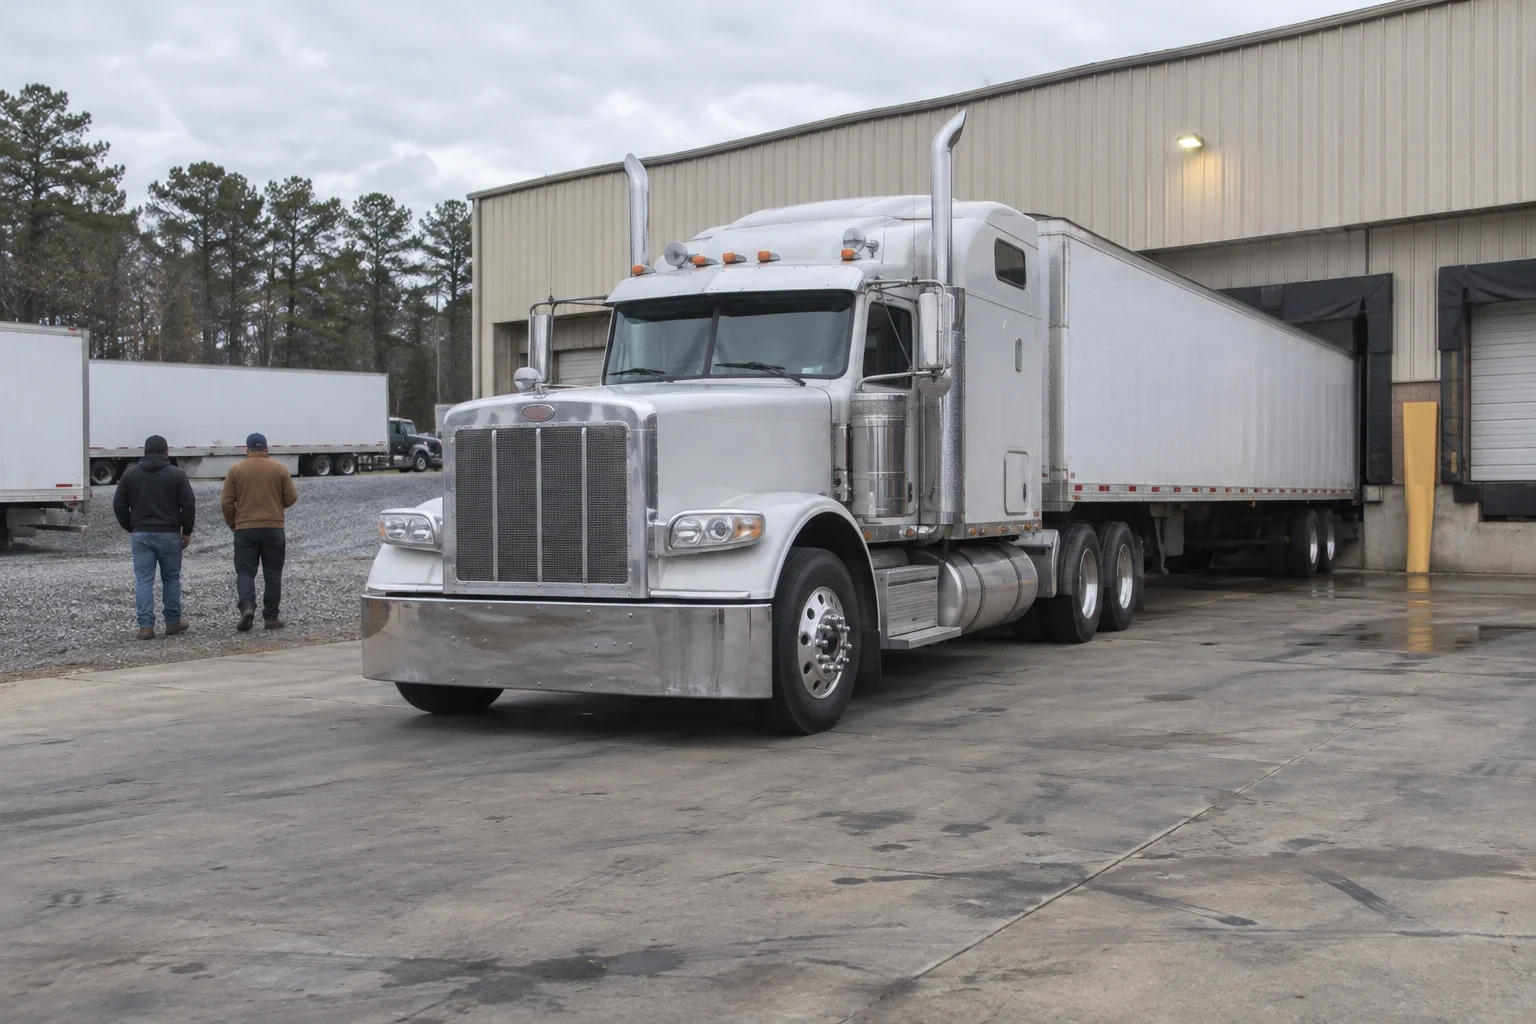
What Moves Your Premium
Trucking premiums are built from a handful of details about your trucks, your drivers and the freight you haul. Two operations with the same truck can see very different quotes. Here is what underwriters look at most closely.
We collect your details by phone, shop the carriers that write your type of operation, and walk through each quote with limits and deductibles side by side. Nothing is bound until you approve it.
- Radius and lanes
- Local work inside a short radius rates differently from regional or long-haul runs. Underwriters also look at where trucks are garaged and the states you run through.
- Drivers and their records
- Years of CDL experience, recent violations and accidents on motor vehicle reports carry a lot of weight. Adding a newer driver can change a fleet quote more than adding a truck.
- Authority age and loss history
- A brand-new MC authority has no track record, so fewer markets will quote and pricing reflects that. Clean loss runs over time open up more options at renewal.
- Truck values and deductibles
- Physical damage premium follows the stated value of each tractor, trailer or straight truck. A higher deductible lowers the premium but raises what you pay out of pocket after a loss.
- What you haul
- Cargo coverage depends on the commodity. Electronics, refrigerated loads and building materials each carry different theft and damage exposure, and some carry exclusions worth knowing about.
- Limits your contracts require
- Brokers, shippers and general contractors often set minimum liability and cargo limits. We quote to those requirements so you can accept the work you are counting on.
Coverage for the Way Your Trucks Run
We are licensed for property and casualty insurance, we have been in business 5 years, and trucking is the work we write. Each policy below answers a different question: who pays when your truck injures someone, when the truck itself is damaged, when the load is lost, or when you are driving off dispatch. We show you where one policy ends and the next begins, so you are not paying twice for the same risk or finding a gap after a claim.
Commercial Trucking Insurance
Liability, cargo, physical damage and the filings behind your authority, quoted by phone with a timeline you can plan your first load around.
Primary Auto Liability
The coverage that pays for injuries and damage your truck causes to others, placed and filed with a clear timeline you can plan your first loads around.
Physical Damage Insurance
Collision and comprehensive coverage for the trucks and trailers you own, with a stated value and deductible set carefully before you ever need them.
Motor Truck Cargo Insurance
Cargo coverage written around the commodities you actually haul, with limits and exclusions explained before a broker or shipper finds the gap.
Non-Trucking Liability
Liability coverage for leased owner-operators driving off dispatch, set to your lease limits with a clear timeline for your certificate of insurance.
Trailer Interchange Insurance
Physical damage coverage for trailers you pull under a written interchange agreement, set up so your certificate is ready before the first hookup.
Owner-Operator Insurance
Coverage for owner-operators leased to a carrier or running their own MC authority, quoted on a timeline we spell out before we start.
New Authority Truck Insurance
Coverage and federal filings for carriers starting under their own MC authority, with clear timing so you know when you can haul.
Fleet Truck Insurance
Coverage for trucking fleets of several units, with one renewal calendar, a current unit and driver schedule, and certificates handled in order.
Dump Truck Insurance
Liability, physical damage and job-site certificates for dump and construction trucks, with honest timelines from first call to bound coverage.
Hotshot Truck Insurance
Coverage for one-ton pickups and flatbed or gooseneck trailers, built around your authority, your loads and the date you need to start hauling.
Box Truck Insurance
Liability, cargo and physical damage for straight trucks running final-mile, furniture, appliance or freight loads, with honest dates for every step.
How a Quote Comes Together
Most of the work happens by phone or video, and you can sit down with us at our office if you prefer. Each step comes with a date so you know what is next.
- 1
The first conversation
We ask for your DOT number and MC authority, the VINs and values of your trucks, your drivers, your radius and what you haul. If you are still waiting on authority, we start with what you have.
- 2
Documents and a target date
We tell you which documents the carriers need, usually CDLs, loss runs and any current policy pages, and give you a realistic date for quotes based on how complete the file is.
- 3
Quotes compared together
We review each option with you by phone or video: limits, deductibles, exclusions and payment terms. If a quote comes back with conditions, we explain them before you decide.
- 4
Binding, filings and certificates
Once you choose, we bind coverage, handle the federal and state filings your authority requires, and issue certificates to the brokers and shippers you name.
- 5
Through the policy year
Adding a truck, removing a driver, or needing a new certificate for a new customer all start with a phone call to us. We note the change, tell you when it will be processed, and confirm when it is done.
A Trucking Agency That Keeps You Informed
We write insurance for owner-operators, new motor carriers, hotshot and box truck operators, dump truck businesses and small to mid-size fleets. That narrow focus means we know which questions an underwriter will ask about your operation and can prepare the answers before the file goes out.
We meet clients at our Mableton office, by phone or over video, whichever fits your week. Many of our clients are on the road during business hours, so we keep conversations short, write down what was agreed, and follow up when we said we would. If something changes on our end, you hear it from us first.
- License
- Licensed for property and casualty insurance
- In business
- In business 5 years
Serving Motor Carriers Across the West Metro
Our office is in Mableton, and we work with trucking operations throughout the surrounding area, including Smyrna, Austell, Lithia Springs, Powder Springs and Douglasville. We also write coverage for carriers based in Marietta, Vinings, Fair Oaks, South Fulton and Atlanta. Because most of our work happens by phone and video, distance rarely changes how quickly we can move.
- Mableton
- Smyrna
- Lithia Springs
- Austell
- Atlanta
- Marietta
- Douglasville
- Powder Springs
- Vinings
- Fair Oaks
- South Fulton
If your trucks are garaged elsewhere in Georgia, give us a call and we will tell you whether our carriers can write your operation.
How We Work With Your Operation
A truck that cannot run because a filing is late costs real money. So we treat dates as seriously as limits and deductibles, and we tell you early when something is going to take longer than planned.
A timeline before we start
On the first call we tell you what the carriers will ask for, when you can expect quotes back, and what usually slows things down, such as missing loss runs or a driver with a recent violation. You can plan your first load or your renewal date around that, not around a guess.
A call when underwriting shifts
Sometimes a market declines, asks for another motor vehicle report, or wants photos of a truck before binding. When that happens we call you that day with what changed and what it means for your start date. You do not find out by watching a deadline pass.
Certificates worked around your pickups
Brokers and shippers often want a certificate of insurance before they release a load. We ask when the pickup is and work requests in that order. If a certificate needs underwriter approval first, for example to name the broker on your policy, we tell you plainly so you can let the broker know.
Coverage explained line by line
We read the parts of a policy that matter on the road: cargo exclusions for unattended trucks or reefer breakdown, how physical damage is valued, and when bobtail coverage stops applying. You buy what your operation needs and nothing it does not.
Renewals started well ahead
We begin renewal work weeks before expiration, gathering loss runs and updated driver lists while there is still time to shop. Quoting against a final-week deadline leaves you with fewer choices.
Questions Truckers Ask Us
How long does it take to get a trucking insurance quote?
It depends on how complete your information is and how many markets fit your operation. An established carrier with clean loss runs and a full driver list moves faster than a brand-new authority. On the first call we give you a realistic date, and if an underwriter needs more time, we call you rather than letting the date slip quietly.
I just received my MC authority. Can you help me get coverage in place?
Yes. New authorities need liability filings in place before the authority can become active, and fewer carriers quote operations with no history. We tell you which documents to gather, which markets are likely to quote, and how long the filing process typically takes, so you can plan your first load with realistic expectations.
What is the difference between primary liability and bobtail coverage?
Primary auto liability covers injury and property damage you cause while operating under your own authority or under dispatch. Non-trucking liability, often called bobtail, covers a leased owner-operator when driving for personal use, off dispatch. The motor carrier you are leased to usually carries the primary liability, which is why the two policies work together.
How quickly can I get a certificate of insurance for a broker?
Standard certificates are usually straightforward once your policy is active. When a broker or shipper wants to be named on your policy as an added party, the carrier may need to approve it first, and that takes longer. Tell us your pickup time when you ask, and we will tell you honestly whether it can be ready by then.
Do I need cargo coverage if my broker has not asked for it?
Most brokers and shippers will ask eventually, and without it you are personally responsible for a damaged or stolen load. We look at what you haul and the typical load value, then explain the exclusions that matter, such as unattended truck theft or refrigeration breakdown, before you choose a limit.
Why did my premium change at renewal?
Common reasons include new violations on a driver's record, a claim during the year, added trucks or higher stated values, a wider radius, or a change in the market. We start renewal work weeks ahead so there is time to review the reasons and shop other carriers if it makes sense.
Do I have to come into the office?
No. Most clients handle everything by phone or video, and we go over each document we need together during the call. You are welcome to meet us at our Mableton office if you prefer to talk in person.
Know Where Your Coverage Stands, and When
Tell us about your trucks, drivers and lanes, and we will give you a clear plan for quotes, filings and certificates, with a date attached to each step.