ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Mableton
We write motor truck cargo insurance around the freight you haul, the limits your brokers require and the exclusions that matter for your loads. You get a clear timeline for your quote and your certificate of insurance, and we tell you if anything changes along the way.
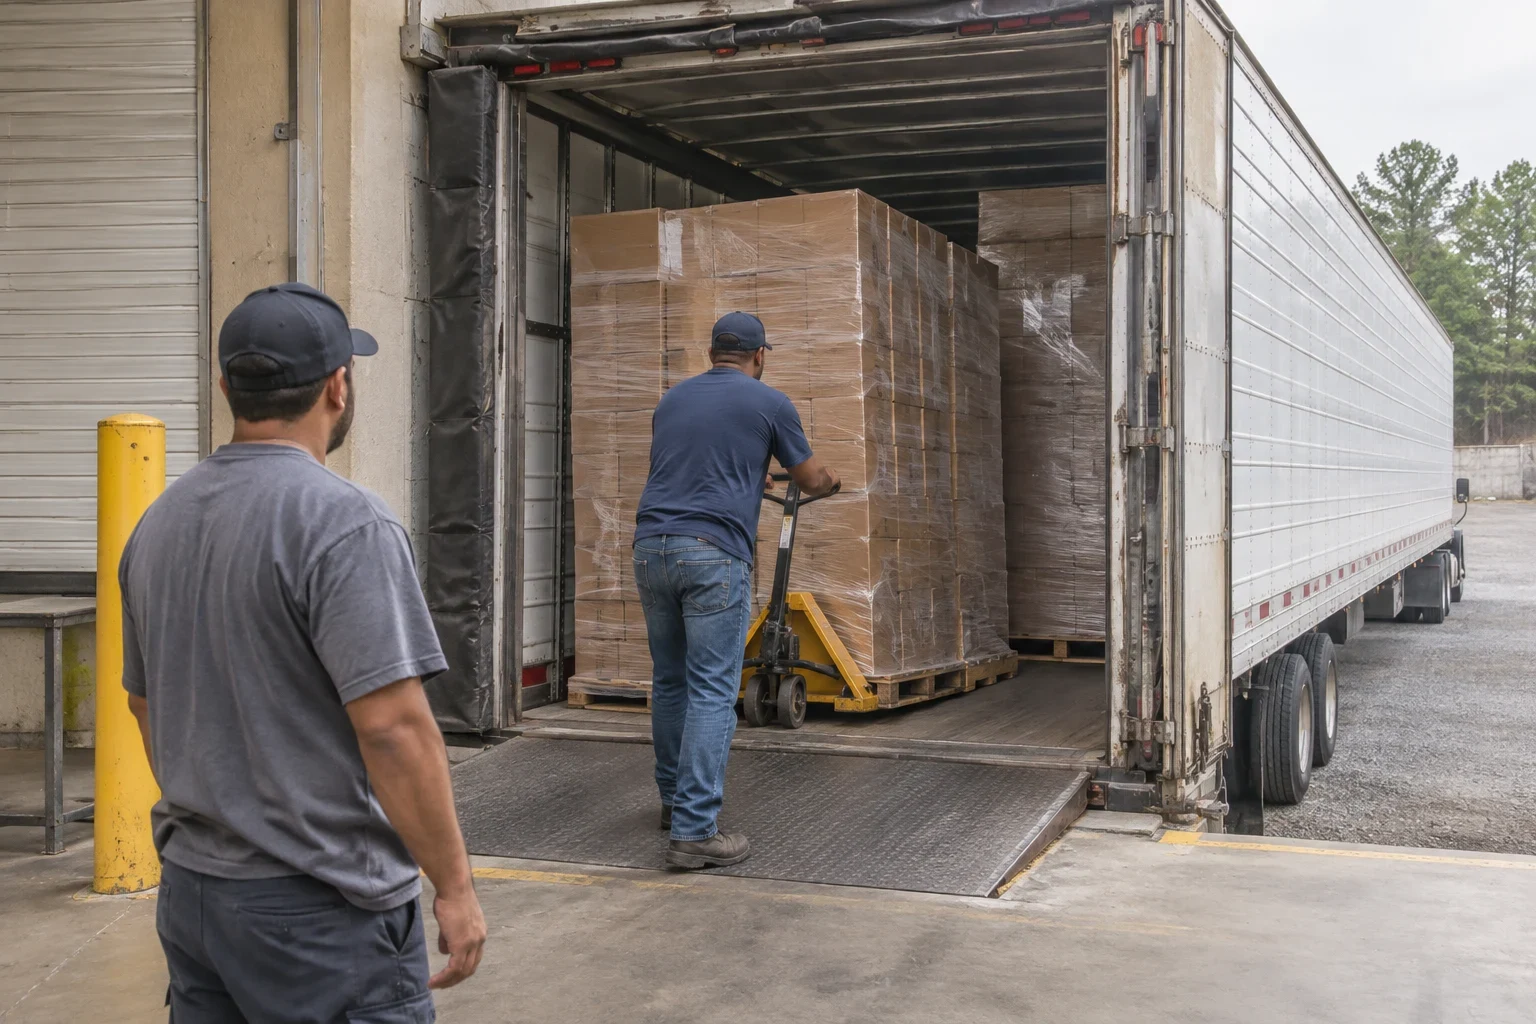
What cargo coverage protects, and when you need it
Motor truck cargo insurance pays for freight in your care when it is lost or damaged in a covered event: a rollover, a fire, a collision, or theft where the policy covers it. It protects the load, not the truck. Your truck is handled under Physical Damage Insurance, and injuries or damage you cause to others fall under Primary Auto Liability Insurance.
Most brokers and shippers will not tender a load until they see cargo coverage on a certificate of insurance with their name on it. If you run under your own MC authority, you need it to book freight. If you lease onto a motor carrier, read the lease to see if their policy extends to your loads or if they expect you to carry your own.
We are licensed for property and casualty insurance and have been in business 5 years, placing coverage for owner-operators and small fleets around Mableton and the west side of Atlanta. Cargo policies vary more than most people expect, so we read the form with you before you sign.
What we work through with you
A commodity review
We list what you haul, how often and for whom. Electronics, alcohol, tobacco, metals and refrigerated goods are often limited or excluded, so the commodity list shapes everything else.
Limits that match your contracts
We compare your limit to what your broker agreements and shipper contracts require. If one customer asks for more than the rest, we look at whether a higher limit or a per-load option makes more sense.
Exclusions in plain words
Unattended-vehicle clauses, reefer breakdown, theft conditions and named-perils wording can turn a claim down. We go through each one so you know where the edges are.
Certificates of insurance
We issue certificates naming your brokers and shippers as holders and tell you how long each request usually takes, so you can plan around a pickup.
Deductible choices
A higher deductible lowers the premium but comes out of your pocket on every claim. We show you the trade so you can pick what fits your cash flow.
Signs your cargo coverage needs attention
A broker rejected your certificate
Usually the limit is too low, the holder name is wrong or the policy shows a commodity exclusion that matches their freight.
You changed what you haul
Moving from dry van general freight to produce, building materials or high-value goods can fall outside your current form. Tell us before the first load, not after.
You added a reefer
Spoilage from refrigeration breakdown is often excluded unless the policy adds it. Many carriers do not find out until a claim.
You are not sure who covers the load
Leased owner-operators sometimes assume the carrier's policy covers them when it does not. A short review clears it up.
Your renewal arrived with new wording
Insurers revise forms. A theft condition or territory limit can change quietly between terms.
How a cargo quote moves from first call to certificate
- 1
The first conversation
By phone, video or at our office, we gather your DOT number, MC authority, commodities, trailer types, lanes and any loss history. We tell you then roughly how long markets will take to respond.
- 2
Going to market
We send your details to insurers that write your type of freight. If an underwriter comes back with questions, we call you rather than letting the file sit.
- 3
Reviewing the options
We lay quotes side by side: limits, deductibles, exclusions and premium. You choose, and we explain what you are giving up with each option.
- 4
Binding and paperwork
Once bound, we issue certificates to the brokers and shippers you name. If an insurer's timing slips, you hear it from us with a new estimate, so you can adjust your load board plans.
What moves the price of cargo insurance
Cargo premiums depend on what is in the trailer and how much of it could be lost at once. Two carriers with identical trucks can pay very different amounts. We show you which factors are driving your number and which ones you can change.
- Commodities
- Theft-prone or fragile freight costs more to cover. Refrigerated loads add spoilage risk.
- Limit and deductible
- A higher limit raises the premium. A higher deductible lowers it but raises what you pay on each claim.
- Loss history
- Prior cargo claims, especially theft or repeat damage, weigh heavily with underwriters.
- Operating experience
- Time under your own authority and driver experience both matter. New authorities often see fewer markets at first, which our New Authority Truck Insurance page covers in more detail.
- Lanes and parking
- Where you run and where loads sit overnight affect theft exposure and how insurers rate the policy.
Cargo insurance questions we hear often
Something not covered here? (770) 338-6428
Does cargo insurance cover my truck too?
No. Cargo coverage pays for the freight. Damage to your tractor or trailer falls under physical damage coverage, which we can quote alongside it.
My broker wants a specific limit. Can you match it?
Usually, yes. Send us the broker agreement or the requirement and we will quote that limit. If a single customer asks for much more than the rest, we will talk through whether it is worth raising the limit across the whole policy.
How long does it take to get a certificate of insurance?
Once a policy is in force, certificates are often quick, but timing depends on the insurer. We tell you the expected turnaround when you ask and update you if it runs longer, so you are not waiting at a dock with no paperwork.
Will my policy cover a stolen load?
It depends on the form. Many policies require the truck to be locked and attended, or parked in a secured lot, for theft to be covered. We read those conditions with you before you bind.
I am leased to a carrier. Do I need my own cargo coverage?
Some carriers cover cargo for their leased owner-operators and some require you to carry it. Check your lease agreement, or share it with us and we will tell you what it says.
Get cargo coverage sorted before your next load
Tell us what you haul and which brokers you work with. We will give you a realistic timeline for quotes and certificates, and keep you updated if anything shifts.